Introduction
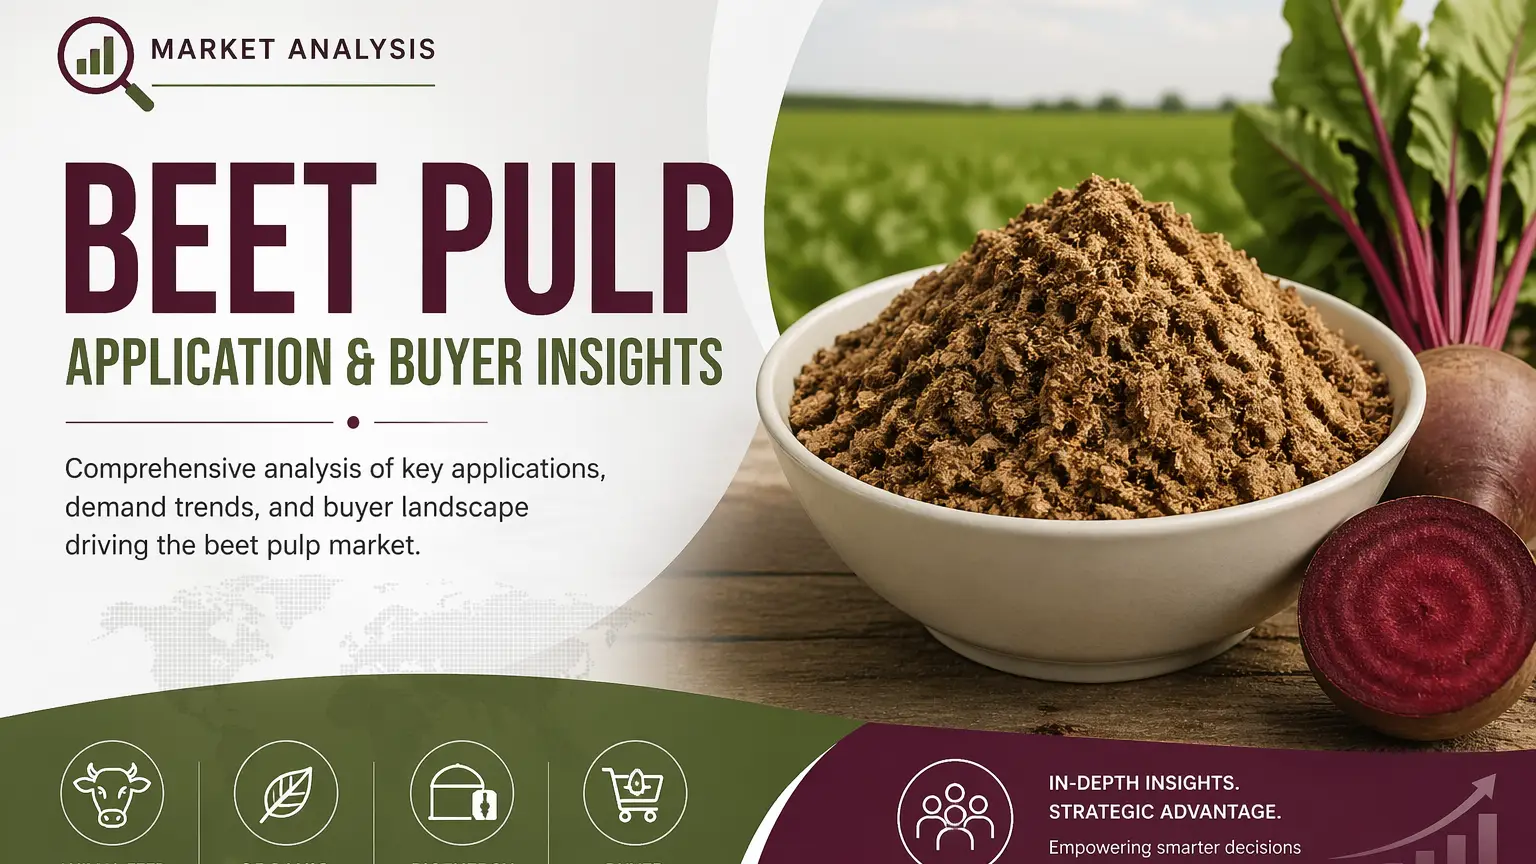
Beet pulp, a fibrous byproduct derived from sugar beet processing, continues to gain strategic importance in the global feed and agri-industrial ecosystem as of 2026. Once considered a low-value residue, it has evolved into a cost-efficient, energy-rich feed ingredient for ruminants and a stabilizing input for circular agricultural value chains. The global beet pulp market is projected to expand at a 5.2% CAGR (2026–2030), supported by rising demand for sustainable livestock nutrition and feed cost optimization. With annual production approaching 28 million MT, beet pulp is now widely traded across Europe, North America, and Asia-Pacific as a standardized commodity with increasing industrial relevance.
Applications in Livestock Nutrition and Feed Innovation
Beet pulp is primarily utilized in ruminant diets, particularly dairy cattle, due to its high digestible fiber content and energy stability. It is also gaining traction in horse nutrition and premium pet food formulations where controlled fermentation benefits are valued. Feed manufacturers increasingly blend beet pulp into compound feeds to enhance gut health and reduce reliance on high-cost grains. Its functional role in improving milk yield efficiency has strengthened its position in modern feed innovation systems.
Expanding Buyer Base Across Agro-Industrial Sectors
The buyer landscape is broadening beyond traditional dairy farms to include integrated feed mills, livestock integrators, and export-oriented agribusinesses. Pet food manufacturers are emerging as high-value buyers, leveraging beet pulp as a fiber stabilizer. Additionally, ethanol and bioenergy producers are exploring its secondary fermentation potential. This diversification is reshaping procurement strategies, particularly in regions with volatile grain supply chains.
Market Dynamics and Regional Production Shifts
Europe remains the dominant production hub due to its established sugar beet processing infrastructure, while the United States maintains steady output driven by Midwestern agro-industrial clusters. Emerging demand in Asia-Pacific, particularly China, is increasingly dependent on imports. Global production concentration continues to stabilize near 28 million MT, though regional reallocation is influenced by sugar policy reforms and climate-driven crop variability.
Pricing Trends and Supply Chain Optimization
Beet pulp pricing remains moderately stable, ranging between USD 180–240/MT (dry pelleted basis) in 2026, depending on moisture content, pellet quality, and origin. Logistics efficiency and proximity to sugar processing plants significantly impact landed costs. Supply chain digitization and bulk handling improvements are helping buyers reduce volatility exposure while improving feed formulation consistency.
Conclusion
The beet pulp market is transitioning from a byproduct-driven segment into a structured global feed commodity with expanding industrial relevance. As sustainability pressures and feed cost optimization intensify, demand visibility remains strong across both developed and emerging markets. In this evolving landscape, integrated sourcing and quality consistency become critical. Companies seeking reliable bulk procurement and global distribution support increasingly turn to established trading partners such as Tradeasia International, which provides end-to-end chemical and feed ingredient supply solutions, ensuring consistent availability and cross-border logistics efficiency for industrial buyers worldwide.
Sources